Search Blog Posts

Showing posts with label Inflation. Show all posts

Sunday, March 8, 2015

▶ Fiat money inflation in France (1789) - Part 2: John Law - Video

embedded captions can be removed/added with tiny "cc" at bottom.


 PART I for a preliminary historical perspective can be viewed here

Uploaded on Jun 15, 2011
Max Keiser, of maxkeiser.com, James Turk, Director of The GoldMoney Foundation and Pierre Jovanovic, jovanovic.com, tell the story of the introduction of Fiat Money to France.

In this episode we look at the use of Fiat Money during the French Revolution and how monetary mismanagement made an already delicate situation even worse, destroying the nation's economy and encouraging political radicalism.

We start with the debates over the issuance of paper money, explaining that the previous experience of John Law made French statesmen like Necker very cautious about fiat currency. The debates over the first issue of assignats were hard fought and lasted a long time, with the first issue of assignats approved by just a handful of votes and with all manner of guarantees to insure that it was "backed" by land and other forms of collateral.

The first issue of assignats had some very positive short term effects, stimulating commerce as paper wealth spread. However, the government took only a few months to spend the money raised and very soon cries were raised for more. This time a new issue was approved by a large majority. We look at how this paper money inflation started to drive prices higher, encouraging the creation of more paper in increasing amounts as the government and its clients became addicted to newly-created money. Rising prices were blamed on all manner of scapegoats in order to divert attention from the real cause: money printing.

As the situation worsened, the worst rose to the top, with Clavière becoming Minister of Finance with the promise to increase printing. Gresham's law started to act in full force, driving good money out of circulation with such force that silver, gold and even copper disappeared from the market. Attempts to put ceilings on prices through the "Law of the Maximum" and to prop up the value of assignats failed, and only succeeded in criminalising most commerce with increasingly harsh penalties -- eventually including death -- for those that sold above established prices or refused to accept payment in worthless government paper. Even the guillotine was not enough backing to ensure the assignat's survival.

Eventually food riots brought down the revolutionary government, and after several interim reactionary governments culminated with Napoleon's military rule. Napoleon brought back the gold standard, which survived until the first World War.


Thursday, February 26, 2015

This Is What Happens To Gold In A Hyperinflationary Currency Crisis: Ukraine Edition

Ukraine Sends Gold to US for "Safekeeping"! Yikes, don't they know the US Fed has Stolen Germany's Gold? ----- March 16. 2014


Dec 4, 2014 ... Who's who in Ukraine's new neo-Nazi, fascist government ... Was The Price Of Ukraine's "Liberation" The Handover Of Its Gold To The Fed?

Aug 11, 2014 ... The Ukraine's gold reserves weigh in at 42.3 tonnes, and are worth 1.3 billion Euros. A leading figure of the former ministry of finance has ...


As Ukraine's socio-economic situation goes from wost to worst-er, today's announcement by President Poroshenko that the government will take actions to stabilize the currency (which as we previously noted, appears to be heading for hyperinflation) has Ukrainians rushing for the exits into precious metals... with only one goal in mind - wealth preservation.

This is what gold does in a fiat-currency crisis. Now if only Ukraine actually still had some gold...

Furthermore, according to RIA, on Tuesday, Ukrainian television channel Ukraina announced that with the new exchange rate, the minimum wage in Ukraine stands at around $42.90 per month, which according to the channel, is lower than in Ghana or Zambia.

There are currently no plans to raise the minimum wage until December.

Behold hyperinflation:
"Food prices among producers rose 57.1 percent, with the price for grains and vegetables rising 91 percent from January 2014 to January 2015, while the official inflation rate over the period totaled 28.5 percent.

Meanwhile, Ukrainian consumers responded to economic difficulties by cutting their spending in hryvnias by 22.6 percent, which amounts to an almost 40 percent decrease in real consumption."

Nothing to fear though: we are sure all that hard-earned US taxpayer-lent money will be safe and sound.

source Zero Hedge

Thursday, January 29, 2015

Comparing the inflated cost of living today from 1938 to 2015: US Dollar losing an enormous amount of purchasing power since 1938

 Posted by mybudget360
 
People have a hard time understanding how inflation erodes their purchasing power.  Little by little the cost of everything goes up and people simply assume this is normal in an economy.  The $2 movie ticket becomes a $8 movie ticket.  That can of tuna just got smaller but the price remains the same.  The cost of going to college went from manageable to needing large student debt merely to complete a four year degree.  Inflation is argued to be a purely monetary outcome.  You have too much money, in the form of cash or credit in today’s case, chasing fewer goods.  In our current economy, debt is the fuel accelerating inflation.  You can see this in items like housing, cars, and college where debt is the primary fuel driving prices higher.  The big problem today is that incomes are simply not rising fast enough to keep up with the rise in other expenses.  Over time, inflation has a big destructive power.  I thought it would be useful to look at the cost of typical items in 1938 and compare them to where things stand in 2015.


Comparing 1938 to 2015

Over a year ago, we looked at some old data and found this to be useful to readers.  I thought it would be helpful to update the data and see where things stand today in 2015.  Someone sent this snapshot of the cost of living in 1938.  It really is fascinating looking at inflation over a very long period of time.  In this case, we are looking at spending pre-World War II.  Most Americans probably have no sense as to what the cost of living was back then since they are mired in the fight of living paycheck to paycheck.
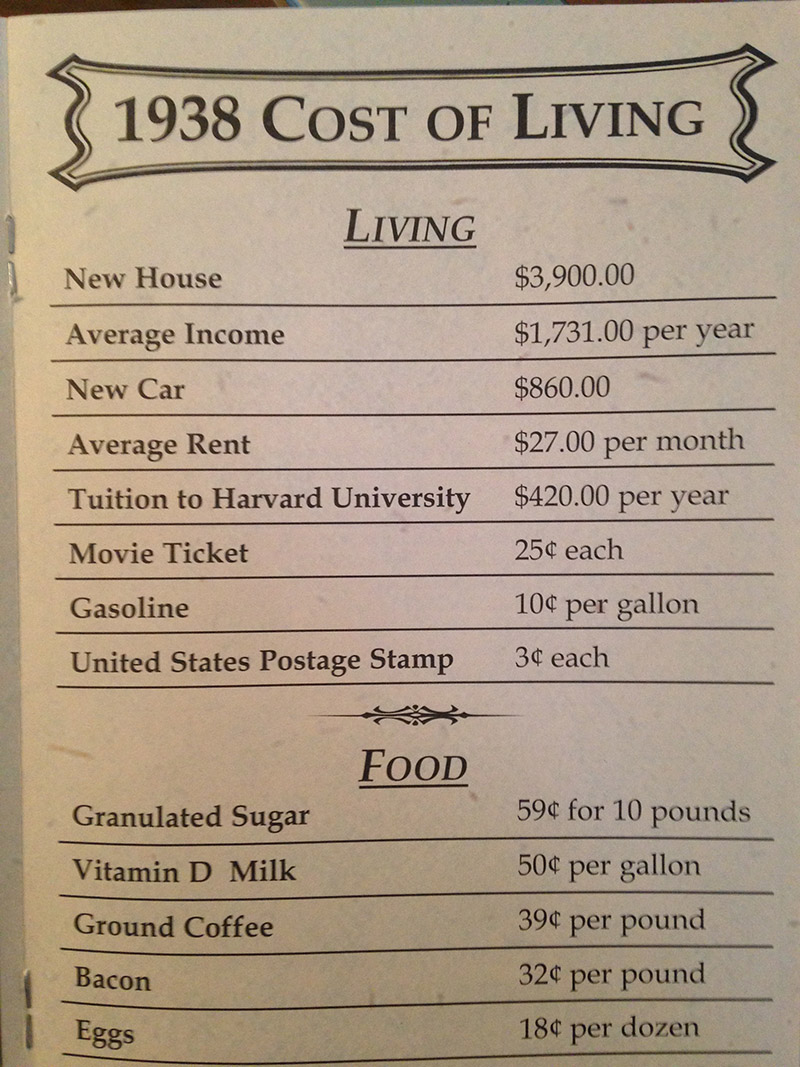
Take a look at the cost of living in 1938:
cost-of-living (1)
Source:  Reddit
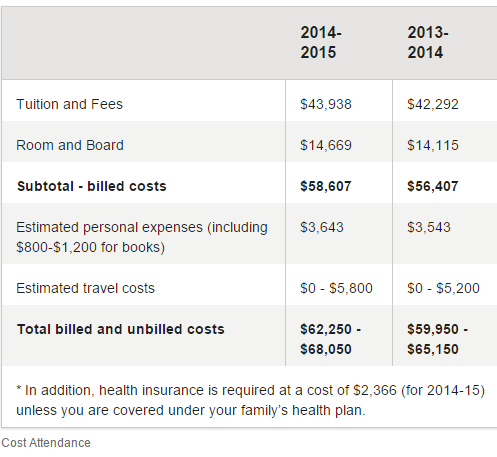
What is important is to look at income in relation to the cost of living.   A new home was about twice the annual average income.  Today, with the median household income being $50,000 and your typical new home costing $298,000 we are definitely on the more expensive side (6 times annual income versus 2 back in 1938).  Look at the new car costs.  A new car cost about $860 or half of annual income.  Today, a regular car can cost $32,000 and most will need to finance it.  Tuition to Harvard was $420 per year and today Harvard tuition is nearly $62,000 with room and board:
harvard
Source:  Harvard website

In other words, the typical family of today would need to use all their annual income to send their kid to Harvard plus go in debt while in 1938, your average family had income to send 4 kids to Harvard per year.  The most inflated of all categories is college tuition.

Looking at various costs adjusting for inflation

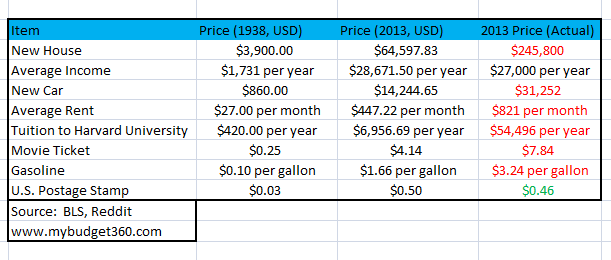
I put this table together and adjusted for inflation to give you a better perspective:
inflation-and-actual-prices
I wanted to update some of this data for 2015 as well:
New house:                        $298,000 (Source: Census)
Average income:              $28,000 (Social Security)
New Car:                             $32,000 (Bankrate)
Average Rent:                   $950
Tuition to Harvard:          See above
Movie ticket:                     $8
Gasoline:                             $1.99
US Postage Stamp:          $0.49
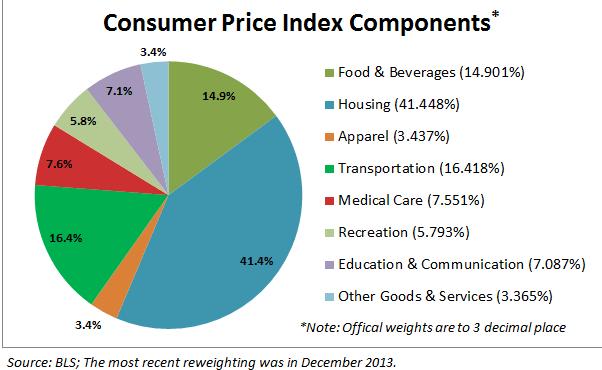
So basically every single category is up besides gasoline given the crash in oil prices in 2014.  But this is a small drop in the bucket given what consumes the biggest portion of your budget:
inflation categories

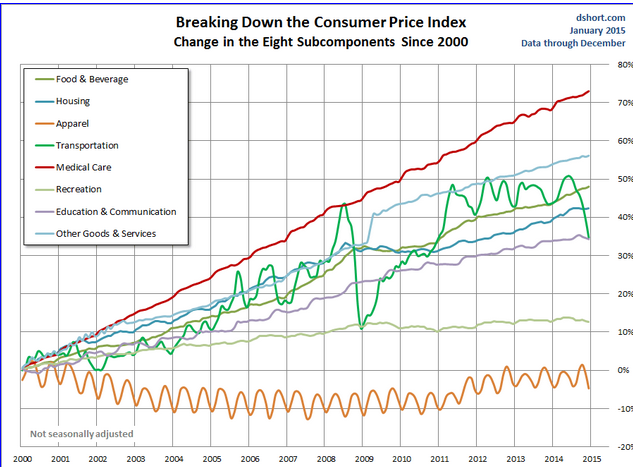
Housing, food, medical care, transportation, and education make up the biggest expenses.  Housing by far consumes the biggest portion.  And look at how fast prices have gone up since 2000:

inflation since 2000
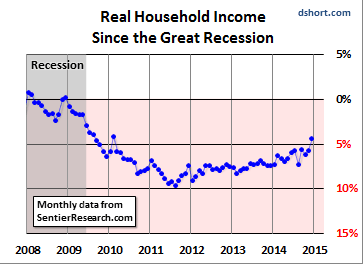
Medical care is up over 70 percent.  Housing is up over 40 percent even with the crash in the housing market.  Basically the only items that held steady were apparel and recreation.  But look at how incomes are doing:
real household income
You wonder why you feel like you have less purchasing power?  You feel poorer because you are thanks to the slow eroding power of inflation.  The Fed would like to argue that there is no inflation but just look at housing costs, medical care, college tuition, and grocery bills and tell the regular working American family that there is no inflation.

Source

Tuesday, January 20, 2015

Larceny in the Heart: The Economics of Satan and the Inflationary State


The Lastest News & Information
January 20, 2015 
Inflation in a Nutshell
by R. J. Rushdoony

Inflation is an act of state, a very highly desirable act of state from the

The rise of the modern totalitarian state has its economic origin in the abandonment of gold coinage for paper money.

As the creator of fiat money, of instant money by means of legalized counterfeiting of wealth, the state is always the wealthiest and most powerful force in society.

As inflation increases, so too does the power of the state. Every civil government thus has a vested interest in inflation. For a state to halt inflation is to diminish its power.

The cry, "Stop inflation," is another way of saying, "Castrate the State," and no state or bureaucracy has yet favored its own castration. 


Thursday, January 1, 2015

Death Penalty for Debasing Currency: US Coinage Act of 1792

Don't kid yourself that it couldn't happen again in this century. The serfs are waking up, and they're MAD as Hell and won't take it anymore. If bankers' heads and those of their government defenders begin appearing on the ends of pikes, you'll know why!

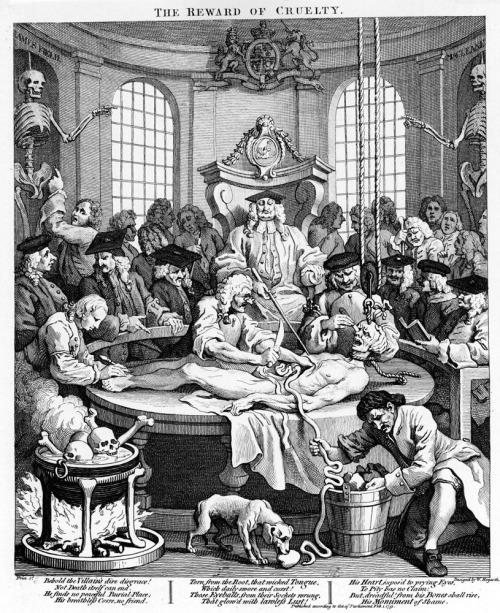
As most of you know much of our current law was based on English case law. Hence, this was the Royal Mint's disposition of counterfeiters and forgers. The methods employed for carrying out the death penalty are appropriate even today.:


SOLOMON IDSWELL, Deception > forgery, 20th May 1795.


Reference Number: t17950520-26
Offence: Deception & forgery
Verdict: Guilty
Punishment: Death


Our preferred method of punishment would be by "dissected and anatomised". Rehabilitation is not up for reconsideration. That's already been shown to be a failed remedy.Plate IV: The Reward of Cruelty by William Hogarth


Section 19 of coinage act of 1792: death penalty for debasing currency

And be it further enacted, That if any of the gold or silver coins which shall be struck or coined at the said mint shall be debased or made worse as to the proportion of the fine gold or fine silver therein contained, or shall be of less weight or value than the same out to be pursuant to the directions of this act, through the default or with the connivance of any of the officers or persons who shall be employed at the said mint, for the purpose of profit or gain, or otherwise with a fraudulent intent, and if any of the said officers or persons shall embezzle any of the metals which shall at any time be committed to their charge for the purpose of being coined, or any of the coins which shall be struck or coined at the said mint, every such officer or person who shall commit any or either of the said offenses, shall be deemed guilty of felony, and shall suffer death. section 19 of coinage act of 1792


The Federal Reserve debased our currency. Take a look at your coinage. See any gold or silver there?

The founders of this nation knew that banks left to themselves, would substitute cheap metal tokens for real money. They had seen it happen in England, and they saw the results; massive unemployment and poverty for the people.

So the Founders created a monetary system based on government-issued currency of fixed real value, for the use of the people without interest. And the United States flourished.

Then the bankers wormed their way back into the system, bought the Congress and a President, replaced the government issued public currency with currency borrowed from their banks at interest... and debased the gold and silver coinage.

By that last act, every member of the Federal Reserve system (and their enablers in Congress and the Treasury) is in violation of Section 19 of the coinage act of 1792.

Source:  section 19 of coinage act of 1792: death penalty for debasing currency

Saturday, December 13, 2014

Central Banking Dysfunction in an Era of Stock Market Volatility


Anthony Wile
A recent article in The Market Oracle caught my eye: "Largest Financial Bubble in History – 10 years of 'Why Sell Now?' "
The article was written this past week during a powerfully slumping market that trimmed hundreds of points off the Dow Jones industrial average. It was written by registered investment advisor Doug Wakefield.

Is this the end of the bull market? I'm not going to forecast short-term ups and downs but the article did remind me once again of the larger dysfunctional nature of our modern financial system.

That's what I want to concentrate on today, for the most part anyway. What I enjoyed the most about the article was its blunt discussion of issues that have received widespread coverage here and that occupy people considerably when it comes to markets and investments.

Most people following these issues would agree that stocks have been propelled forward by a variety of methods including significant asset inflation and regulatory changes that make investing easier. But when will these maneuverings lose their impact? This is no hypothetical question, as we've been reminded once again.

A recent article posted at CNBC entitled "Stocks slide with oil; triple-digit losses for Dow" summarized some of the damage that took place this past week.

U.S. stocks declined on Friday, with benchmark indexes headed for sizable weekly losses, as crude's ongoing slide rattled investors.

"This started a week or so ago, we'd recovered from the October low to a level that is arguably overvalued, and when we're overvalued everything has to go right, and what's not going right is what's happening to the price of oil, and what that means for Russia, Europe and the U.S.," said Hugh Johnson, chairman of Hugh Johnson Advisors.

"Everybody likes to say the price decline in oil is good news for the U.S. economy, but the real issue is this is really bad news for Russia, and by implication, bad news for Europe, which does a lot of business with Russia," said Johnson.

The article makes the point that it is the slumping price of oil that is driving negative stock market action. The concern weighing on the market involves a slowdown in Europe as a result of lower oil prices. The more optimistic story involves a continued "recovery" in the US based on the same price erosion.

Of course, these price movements do not exist in a vacuum. It may be that Western oil prices have slumped at least for the moment based on powerful interests determined to make it more difficult for Vladimir Putin and Russia to recover from various Western embargos.

Why does the West currently seek low oil prices, if it does? Well, one reason is because Putin is said to be buying gold with US dollars and by trimming the price of oil, Western powers are reducing a main source of revenue.

This is just one example of how markets and commodity prices may be subject to larger socioeconomic, political and military considerations. And one can make the argument that major stock markets are extremely vulnerable to such manipulations.

But the biggest manipulation of all is central banking. Central banks – and there are now some 150 of them – are said to have printed something like US$ 50 trillion in the past years since the 2008 financial crisis.

This unimaginable torrent of money has inflated markets around the world and especially in the US. Wakefield's article is persuasive because he reminds us of the probable outcome of this kind of massive monetary inflation.

He writes: "While finding the end of the largest financial bubble in history has proved very illusive over the last three years for some of the most seasoned market technicians in the world, the last fifteen have allowed us to have many reminders that wild rides to the top have always ended the same."

And he cites the following facts to impress upon us the rapidity with which markets can move: "In January of 2006, investors opened an average of 2,708 brokerage accounts per day. By August of 2007, the average had grown to 450,000 individuals accounts opened per day."
... As we head for the close of 2014, and looking at current and former rapidly rising price movements, would one really be all that surprised to find 2015 radically different from the last few years? Considering how much debt has been created merely to stall this "all time high" bubble, would we not expect the downside of financial assets globally to be extremely severe?

He also cites a Bloomberg article entitled "Global Debt Exceeds $100 Trillion as Governments Binge, BIS Says ..."

The amount of debt globally has soared ... to $100 trillion since the first signs of the financial crisis as governments borrowed to pull their economies out of recession and companies took advantage of record low interest rates, according to the Bank of International Settlements.

... Borrowing has soared as central banks suppress benchmark interest rates to spur growth after the U.S. subprime mortgage market collapsed and Lehman Brothers Holdings Inc.'s bankruptcy sent the world into its worst financial crisis since the Great Depression.....

... One thing is for certain. The memory of the 83% decline in the NASDAQ between 2000 and 2002 has long since been forgotten in a world of "money for nothing".

Well ... it hasn't been forgotten this week! And we've always kept it well in mind. We're quite aware of inflation-based market volatility. We've pointed out how orchestrated this stock market run-up has been and how averages are manipulated by central banks themselves that have admitted to interfering directly in the stock market.

That said, we've also predicted that the current "Wall Street Party" might end imminently – or might NOT. We're past the peak volatility months of October and November and markets – absent yesterday's horrendous price action and anomalous oil deflation – usually tend to stabilize late in the year.

Of course, Black Swan events can likely trigger a market meltdown at any point. Let's see what next week brings. Maybe more volatility or a considerable slump? Despite volatility, Western marts may be positioned for continued progress, lubricated of course by tremendous amounts of additional money printing.

We no longer live in a time when we can calculate market forces to aid in our predictions. Instead, we must turn to strategies such as our VESTS model that seek to evaluate what powerful market participants intend to accomplish in an Internet era that makes such manipulations more difficult via increased transparency.
A sad new era. Like you, I accommodate myself to it. Reality is what it is. But the control that central bankers and their colleagues have over markets, monetary policy and more, is in the long run a-historical and intolerable.

The damages are already clear to some, but for most, once this market breaks, a vivid new reality will come into focus... one that will include massive discontent and, to be gentle about it... widespread civil unrest. You won't need a zoom lens to see it.

The larger point to keep in mind? This is an extremely unstable and culturally corrosive system. There is absolutely no justification for concentrating so much monetary power in so few hands. It cannot stand.

And it will not. At High Alert we suggest that protecting one's assets and family mobility are essential at this time... prudent at all times, but even more so now.

Merry Christmas! We are pleased to announce that High Alert Investment Management will be launching a new, more robust Daily Bell website on December 24th. You can expect High Alert to introduce you to ideas and solutions that can help you protect your assets, grow your wealth or enhance and ensure your lifestyle.
Source TheDailyBell

Sunday, November 30, 2014

Video series by Eric deCarbonnel of Market Skeptics about the Exchange Stabilization Fund

1st posted by CV  Wednesday, December 14, 2011

After posting yesterday TheDailyBell's informative reference to deCarbonnel & his videos, I was reluctant to belabor the issue, but a well-informed subscriber  prodded me, so here we go.

From Don't Tread on Me
My Critique of “What I Have Been Afraid To Blog About: The ESF and Its History.”

This is a very interesting video series by Eric deCarbonnel of Market Skeptics about the Exchange Stabilization Fund. It is a look into the secret slush fund that operates trillions of dollars of with no oversight. It is the nexus of money and the dark world of market intervention, covert operation, drug and other illicit activities the Elite run. The real purpose of this video series is very unsettling and turns out to be a very crafty piece of propaganda.

Wednesday, November 12, 2014

Commodity Prices in US Dollars 1831-1881, Gold @US$20.67

All prices for all commodities were remarkably stable during this period in which gold was fixed at US$20.67 per ounce by the US Treasury from the time of our country's founding. Gold remained at that price until Congress surrendered its authority to the Federal Reserve in 1913. So, an ounce of gold would have exchanged for 20 silver dollars. This means of commerce would have been accurately termed a "Gold Coin Exchange Standard", and NOT a "gold standard", as the money was in the hands of the people. 

Note particularly the surge of commodities in gold terms, especially cotton during the US Civil War (1861-1865 + military occupation until 1877) and the North's blockade of the Confederate southern ports. What had been the cotton price range of .06-.10 gold cts/lb suddenly powered ahead to over .55 in 1863. Mark this down in your history textbook margins as the first unprovoked and US Constitutionally unlawful invasion (Mexican War excluded) by the United States of a foreign and sovereign nation.

Keep this in mind as we come up on the Fed's 100 year anniversary this December.

Thursday, November 6, 2014

It seems nuts, but the Swiss may go back to a gold standard

It ain't "nuts" to sound money folks like us.


The British pound hasn’t been linked to gold since 1931. The US snipped the cord in 1971. But the Swiss only fully severed ties to gold in 1999, when voters approved a revamped constitution.


Now, a good chunk of them seems to want to go back.


On Nov. 30, Swiss voters will cast ballots on a number of issues including the “Save our Swiss Gold” initiative launched by the right-leaning Swiss People’s Party. The ballot measure would instantly ban the Swiss National Bank from selling gold. It also would require that the national bank keep 20% of its assets in gold within five years. (It currently has about 8% in gold.) Oh, and it would demand that all the gold be stored in Switzerland itself. (About 30% is parked abroad right now.)


“It’s really an attempt to return to some kind of gold standard, for those who don’t trust paper money and who want gold backing it up,” UBS strategist Beat Siegenthaler told Reuters.


While it’s not strictly the same thing as a gold standard—for instance a classical gold standard stipulated that national banknotes be freely converted to gold at a fixed price—the Swiss gold initiative is a step in that direction.

What’s the motivation, exactly?


It would be one thing if we were dealing with a basket-case currency and rampant Swiss inflation. But Switzerland’s currency problem, ever since it cut ties with gold, is that the franc has been far too strong, not too weak. That’s acted as a drag on the Swiss economy’s high-value export sector. In fact, it’s been such a problem that the Swiss National Bank has taken big—some might say risky—steps to smack down the currency, the effects of which would likely be reversed if the bank were forced to buy more gold.


As for the repatriation stipulation, if Switzerland’s vast holdings of gold were parked with the Central Bank of Argentina, well, ok then. 

But the Swiss National Bank says 70% of its gold already is in Switzerland, while the rest is slumbering quietly at the Bank of England (which holds 20%) and the Bank of Canada (with 10%), not exactly the most heterodox institutions in the world.


And the worst part of the proposed law, according to a Swiss National Bank official by the name of Jean-Pierre Danthine, is the provision that Switzerland must never, ever sell gold again. He explained in a recent speech:

In combination with the obligation to hold at least 20% of total assets in gold, this could gradually lead the SNB into a situation where its assets would mainly consist of gold: each extension of the balance sheet for monetary policy reasons would necessitate gold purchases, but whenever the balance sheet needed to be reduced again for the same reasons, we would not be able to resell our gold holdings. This would severely restrict our room for manoeuvre.


From a purely tactical point of view, it would be deeply silly to double down right now on gold, which gained in value during the financial crisis but has since slid from its peak in 2011 at nearly $1,900 an ounce. Committing to buy now would essentially be a giant bailout for speculators in the gold markets. Bloomberg reports that, given the Swiss National Bank has some $544 billion in assets on its balance sheet, the gold initiative would force it to buy more than $56 billion worth of physical gold over the next five years. And if current price trends continue, the value of that gold would be falling.
 
In short, the Save Our Swiss Gold initiative doesn’t make sense economically. (Luckily its chances of becoming law are slim—it would need to win outright in a popular vote, and also in the majority of cantons that make up the Swiss Federation.) But referenda like this and the one Swiss voters recently passed to clamp down on immigration really aren’t about economics. They’re about the increasingly influential rightward drift of European politics, which threatens to result—especially in the case of the Save our Swiss Gold initiative—in some really terrible policies.
via qz.com

Tuesday, October 7, 2014

Dollar Going Supernova then Black-Rob Kirby

4th


By Greg Hunter’s USAWatchdog.com (Early Sunday Release)


Derivative and gold expert Rob Kirby says the U.S. looks a lot like the run up to the fall of Rome more than 1,500 years ago.  Kirby explains, “The parallels with what we are experiencing today are so clear and so much like what was happening in Rome as Rome was falling.  Diversions were the way of the day, anything to divert people’s attention from the undermining of the empire.  It was largely a financial debasement.  Rome fell when they debased the currency.  That’s the major factor behind the fall of the Roman Empire.  It was the debasement of the currency, and we are seeing the same thing today.  What’s at the heart of all these issues?  What’s at the heart of all the trouble in the world right now?  The world’s reserve currency has been debased to the point that it is going to go supernova.  

This is the whole illusion behind the strength of the dollar.  The dollar isn’t getting stronger, just like stars aren’t going to have longevity when they go supernova.  They get brighter and you might think the star is getting more viable when, in reality, the notion of it getting really bright before it goes supernova is exactly the opposite of the illusion of it getting brighter.  It’s what happens just before it goes black and dies.”

When will the powers that be pull the plug?  Kirby says, “They won’t willingly pull the plug.  What they are looking to do is create a diversion where they can pose themselves as the savior.  People refer to it as problem, reaction, solution.  They create a false flag to create a diversion of the underlying real problem, which is the debasement of the currency, and then they pose as the saviors or the Johnny-on-the-spot with the solution to the false flag that has been manufactured. Through this process, people tend to lose their civil liberties and their freedoms and their ability to be an opposition of any kind.”

On gold and silver prices, Kirby knows the prices are heading up despite the recent knock down in prices for both metals.  Why is he so bullish?  Kirby says, “The reason I say this is because I know people that are in the business of procuring (physical gold and silver) massive amounts with mega money behind them in the physical market, and I know these people are still accumulating everything they can lay their hands on.  

They can’t lay their hands on enough (metal) to satiate the resources they have to work in that area.  Their ability to acquire physical metal is becoming harder and harder and harder as time goes on.  This is in spite of paper prices being knocked down.  It is in spite of business networks in the mainstream media . . . erroneously report that people want less physical bullion, and that’s why the price is going down.  That is a lie.  The reality is people who are in the market for physical metal can’t get enough.  It is being misreported, and we are being sold a bill of goods by our mainstream media.   The mainstream media is in bed with the ruling elites.  At the end of the day, physical metal will trump the paper.”

When does the paper manipulation in the gold and silver markets end?  Kirby says, “I still think we see major dislocations before the end of the year.  I believe people who have contracted for physical metal are going to be denied their deliveries before the end of the year.  I think this will go very public, and it’s going to lay bare the abject fraud that has been occurring with the smash down in the paper price (of gold and silver.)  The disconnect between the paper price and the lack of physical metal is going to manifest itself in a big way before the end of the year.”  Kirby goes on to say that when gold and silver bullion contracts go unfilled with physical metal, the jilted buyers will go public in a big way, and Kirby predicts, “That’s how it ends, and I think it comes this year. . . . I do think the fuse is that short now.”

Join Greg Hunter as he goes One-on-One with Rob Kirby of KirbyAnalytics.com. 
(There is much, much more in the video interview.)
After the Interview: 
Kirby says, “Something is going to break and crash the financial system, cause WWIII or both.”  Kirby says he can think of at least 10 things that could be the trigger for this calamity.
Kirby has lots of free information on KirbyAnalytics.com.  Kirby also has a newsletter subscription service that delivers detailed analysis every two weeks for a fee of $145 a year.  If you would like to sign up, please click here.

Sunday, October 5, 2014

VIDEO: A National Failure to Save & Invest

As detailed in earlier chapters, the US’ debts and unfunded liabilities far exceed its assets. But making matters worse, the country is suffering from a prolonged failure to save and invest — both at the personal and national level.

Being over-indebted and under-capitalized is a recipe for hardship as we move into the future, especially if economic growth is going to be harder to come by (which we forecast in the upcoming chapters on net energy). Each year we continue this deficit makes us less able to withstand systemic shocks (a 2008-style financial crisis, an energy shock, the outbreak of war), some number of which lie undoubtedly ahead at some point.

How did we get to this point? Do we really want to pass these problems along to future generations? Questions like these should be front and center in the national debate, but sadly, are not. We need to work to change that — and in the interim, lead by example at the individual level.


For the best viewing experience, watch the above video in hi-definition (HD) and in expanded screen mode

Coming next Friday: Chapter 17: Bubbles

For those who simply don’t want to wait until the end of the year to view the entire new series, you can indulge your binge-watching craving by enrolling to PeakProsperity.com. The entire full new series, all 27 chapters of it, is available — now– to our enrolled users.

The full suite of chapters in this new Crash Course series can be found at www.peakprosperity.com/crashcourse
And for those who have yet to view it, be sure to watch the ‘Accelerated’ Crash Course — the under-1-hour condensation of the new 4.5-hour series. It’s a great vehicle for introducing new eyes to this material.

Friday, August 29, 2014

The Myth of the Unchanging Value of Gold

Mises Daily: Friday, August 29, 2014 by
 

According to mainstream economics textbooks, one of the primary functions of money is to measure the value of goods and services exchanged on the market. A typical statement of this view is given by Frederic Mishkin in his textbook on money and banking. "[M]oney ... is used to measure value in the economy," he claims. "We measure the value of goods and services in terms of money, just as we measure weight in terms of pounds and distance in terms of miles."

When money is conceived as a measure of value, the policy implication is that one of the primary objectives of the central bank should be to maintain a stable price level. This supposedly will remove inflationary noise from the economy and ensure that any changes in money prices that do occur tend to reflect a change in the relative values of goods and services to consumers. Thus, for mainstream economists, stabilizing a price index based on a basket of arbitrarily selected and weighted consumer goods, e.g., the CPI, the core CPI, the Personal Consumption Expenditure (CPE), etc., is a prerequisite for rendering money a more or less fixed yardstick for measuring value.

This idea — that a series of acts involving interpersonal exchange of certain sums of money for quantities of various goods by diverse agents over a given period of time somehow yields a measure of value — is another ancient fallacy that can be traced back to John Law. Law repeatedly referred to money as "the measure by which goods are valued." This fallacy has been refuted elsewhere and rests on the assumption that the act of measurement involves the comparison of one thing to another thing that has an objective existence, and whose relevant physical dimensions and causal relationships with other physical phenomena are absolutely fixed and invariant to the passage of time, like a yardstick or a column of mercury.

In fact, the value an individual attaches to a given sum of money or to any kind of good is based on a subjective judgment and is without physical dimensions. As such the value of money varies from moment to moment and between different individuals. The price paid for a good in a concrete act of exchange does not measure the good's value; rather it expresses the fact that the buyer and the seller value the money and the price paid in inverse order. For this reason neither money nor any other good can ever serve as a measure of value.

Unfortunately, advocates of a gold-price target wholeheartedly embrace this mainstream doctrine while giving it an odd twist. They begin with the wholly unsupported assumption that one commodity, gold, is stable in value and that, therefore it can serve as the lone guiding star — or "The Monetary Polaris" as Nathan Lewis terms it — for Fed monetary policy. According to Steve Forbes, writing in the introduction to Lewis's Gold: The Monetary Polaris, real gold standards have one thing in common: "They use gold as a measuring rod to keep the value of money stable. Why? Because the yellow metal keeps its intrinsic value better than anything on the planet."


Wednesday, August 27, 2014

Silver Price: When is the big comeback?

Wednesday, August 27, 2014, 13:40 clock


After the dramatic rally three years ago, it's been pretty quiet around the silver. Even in the recent geopolitical turmoil, the precious metal could hardly score. When is the big silver comeback?
Silbermix
While the price of gold in the environment of rising political tensions in the crisis areas last grew again, the silver price fell short of the expectations of many precious metal investors.

In this case, both metals are bought by investors as insurance against inflation. That silver is stronger than gold, also used in industry, is one of the main differences between the metals. And this is certainly one of the factors that currently dampens the demand for silver. Since the beginning of silver has now again a drop of approximately 0.5 percent   recorded, for a fat discount of more than 37 percent last year. Gold was down almost 7 percent, however so far after all. In euro terms, the impact is down even slightly larger.

The price of silver is much more volatile compared to other metals.  
That is, the prices more volatile than about in gold. The value of relationship to each other is changing so continuously. To close on a negative or positive evaluation of one metal over the other, one examines the so-called gold-silver ratio. It is a simple ratio: gold price divided by silver price. The gold-silver ratio indicates with how many ounces of silver can buy one ounce of gold. Currently, we obtain for one unit of gold about 65 units of silver (gold-silver ratio = 65). Is silver to gold has to be classed as rather expensive or cheap?
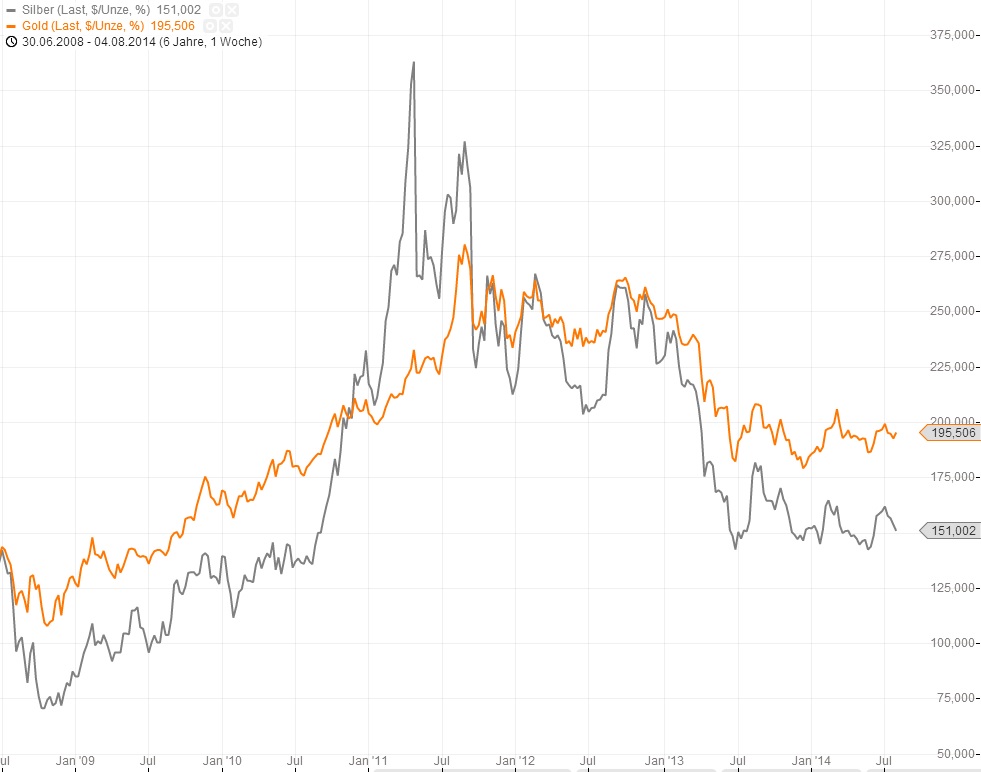
Gold-silver since 2009
Gold and silver price performance since 2009 in comparison (weekly closing prices, index)

For this one must seek the story and compare the geological conditions. According to scientific estimates, more silver is about 17 times stored as gold in the earth's crust. That alone already points to a mismatch between the current precious metal prices. It should however be borne in mind that silver is used industrially.  

The quantities of ore once funded take so continuously. In contrast, all gold ever mined is still as good as being completely present.

More meaningful is the historical comparison. The gold-silver ratio was about 10 to 20 centuries peak periods experienced the quotient end of the 20s and beginning of the nineties, with values ​​of about 100 The sharp rise in the 20th century is due to the fact that silver completely its cash function was robbed and it is now primarily viewed as an industrial metal. The central banks have large holdings of precious metals, but silver is not among them!

The silver market is also regarded as even more strongly influenced by speculative interests, than the gold market. In the spring of 2010 for the first time media attention manipulation allegations were against large U.S. banks (JP Morgan, HSBC) pronounced and later prosecuted, put the price of silver in the episode a dramatic rally on the dance floor.

Within just one year, the price of silver rose from $ 18 to $ 48. Since then, the silver chart is again in decline. So when is the big comeback? U.S. analysts such as Ted Butler and James Turk expect it for a long time. They assume that the current price represents the true scarcity of the precious metal is not nearly. Sooner or later become a new price jump coming - also in relation to gold. It seems as if only someone would take their foot off the gas. And perhaps, have to force a U.S. bank to again before the price of the white precious metal really picks up speed again.


​source: Gold Reporter

CFR Suggests That Central Banks Print Money and Hand It Out Directly to Consumers

By Staff News & Analysis - August 27, 2014

It Begins: Council On Foreign Relations Proposes That "Central Banks Should Hand Consumers Cash Directly" ... A year ago, when it became abundantly clear that all of the Fed's attempts to boost the economy have failed, leading instead to a record divergence between the "1%" who were benefiting from the Fed's artificial inflation of financial assets ... and everyone else, we wrote that "Bernanke's Helicopter Is Warming Up." ... It's well past time, then, for U.S. policymakers -- as well as their counterparts in other developed countries -- to consider a version of [these] helicopter drops. In the short term, such cash transfers could jump-start the economy. Over the long term, they could reduce dependence on the banking system for growth and reverse the trend of rising inequality. The transfers wouldn't cause damaging inflation, and few doubt that they would work. The only real question is why no government has tried them. – Foreign Affairs at ZeroHedge

Dominant Social Theme: Give them all a living wage and do it now!

Free-Market Analysis: The high-profile website ZeroHedge caused a stir yesterday by presenting an article (see above) that appeared in the CFR's Foreign Affairs magazine.

The article called for the Federal Reserve to hand out money directly to consumers.

Wow.

The article was of interest to us because of the bluntness of the remedy and also because it further advanced several elite dominant social themes that we've been analyzing for months.

As predicted, there is a new strategy at work, one that has now predictably included Foreign Affairs. The strategy involves the propagation of two memes: "income inequality" and its putative solution, the "universal basic income."

These memes are being proposed in the top news media around the country, as we've already shown, and now they are growing closer to actionable events. Foreign Affairs is a policy-making facility. Next stop? Perhaps the legislature itself.

They're moving fast – faster and faster. Occupy Wall Street was an elite-controlled populist movement that has seemingly fizzled. But it hasn't taken long to reconstitute the desired memes and reposition them as high-row economic concepts endorsed by "Nobel" laureates among others.

What's the desired outcome of all this? As near as we can tell, one intention was to distract people's attention from the dysfunction of monopoly central banking by blaming economic difficulties on the "one percent." Call this the "French Revolution" gambit.

But now the top elites that organize these promotions seem to have reversed course. Instead of distracting people from central banking, the idea now seems to be to glorify the mechanism.

Here's more from ZeroHedge:
Moments ago a stunning article appearing in the "Foreign Affairs" publication of the influential and policy-setting Council of Foreign Relations, titled "Print Less but Transfer More: Why Central Banks Should Give Money Directly to the People."

In it we read the now conventional admission of failure by Keynesians, who however, unwilling to actually admit they have been wrong, urge the even more conventional solution: do more of the same that has lead to the current financial cataclysm, only in this case the authors advocate no longer pretending that the traditional monetary channels work but to, literally, paradrop money.

To wit:

"To some extent, low inflation reflects intense competition in an increasingly globalized economy. But it also occurs when people and businesses are too hesitant to spend their money, which keeps unemployment high and wage growth low. In the eurozone, inflation has recently dropped perilously close to zero. And some countries, such as Portugal and Spain, may already be experiencing deflation. At best, the current policies are not working; at worst, they will lead to further instability and prolonged stagnation.

"Governments must do better. Rather than trying to spur private-sector spending through asset purchases or interest-rate changes, central banks, such as the Fed, should hand consumers cash directly. In practice, this policy could take the form of giving central banks the ability to hand their countries' tax-paying households a certain amount of money. The government could distribute cash equally to all households or, even better, aim for the bottom 80 percent of households in terms of income. Targeting those who earn the least would have two primary benefits. For one thing, lower-income households are more prone to consume, so they would provide a greater boost to spending. For another, the policy would offset rising income inequality."

This is pretty incredible stuff. We've always maintained that central banks will NEVER print money directly for individual consumers because to do so would be to reveal the mysterious motor at the heart of the modern economy. So what gives the Big Brains behind this central banking paradigm the idea that handing out money directly to consumers will somehow stimulate stagnant economies while palliating the lower classes that are apparently to be targeted for such a giveaway?

It's kinda, well ... crazy.

Do those suggesting this actually think that people will be satisfied with a relative pittance (no matter how generous) once they realize that those in control of the money apparatus can basically print trillions for themselves and their friends?

And what about others who don't receive a similar stipend? These individuals would probably be irritated that they are not qualifying and also increasingly upset about the banking mechanism itself – as it went to work, handing out money to lucky recipients.

The article reads more like a satire or parody than a serious suggestion. But we live in incredible times. The globalist crowd seems increasingly panicked by the Internet and how it has exposed internationalism generally and specific promotions as well.

Whether it is economic stagnation or a widening of the war on terror, people are increasingly skeptical that disastrous economic and military events are either accidental or inevitable. Increasingly a connection is being made between elite internationalism and the themes (and events) intended to push middle classes into giving up power and authority to globalist facilities.

Put it bluntly: The idea that Foreign Affairs writers and editors believe that freely handing out currency is going to strengthen the economy and solidify good will for the current central banking system is either naïve or sinister.

We arrive at the possibility of "sinister" because it appears to us that the globalists have perhaps given up on arriving at a more structured and rationalized internationalism via stealth. Instead, they are apparently moving forward with the age-old tools of economic ruin and military engagement.

Giving away currency would surely be another step toward destroying the modern system and setting the stage for a new one, presumably even more internationalist. Either way, this "trial balloon," if that is what it is, is surely not intended to achieve the real-world results its proponents are arguing for. We can't see it ending well.

Apparently, the remnants of Occupy Wall Street may be gearing up to propose a "debt jubilee" and perhaps this idea of a currency giveaway is supposed to find a place within the larger promotion. 

But if this is to be one of the "solutions" to the "income inequality" meme, it strikes us that those producing these promotions have virtually lost the plot.

Conclusion

We'll see how all this plays out in autumn. Interesting times.

S​ource ​: TheDailyBell

Sunday, August 24, 2014

The Real Value of What $100 Buys in Each State


August 18, 2014

Update: For an additional map that breaks the data down by metropolitan statistical areas, click here.


This week's tax map shows the real value of $100 in each state. Because average prices for similar goods are much higher in California or New York than in Mississippi or South Dakota, the same amount of dollars will buy you comparatively less in the high-price states, or comparatively more in low-price states. Using data from the Bureau of Economic Analysis that we've written about previously, we adjust the value of $100 to reflect how prices are different in each state.

For example, Tennessee is a low-price state, where $100 will buy what would cost $110.25 in another state that is closer to the national average. You can think of this as meaning that Tennesseans are about ten percent richer than their nominal incomes suggest.

The states where $100 is worth the least are the District of Columbia ($84.60), Hawaii ($85.32), New York ($86.66), New Jersey ($87.64), and California ($88.57). That same money goes the furthest in Mississippi ($115.74), Arkansas ($114.16), Missouri ($113.51), Alabama (113.51), and South Dakota ($113.38).


Regional price differences are strikingly large, and have serious policy implications. The same amount of dollars are worth almost 40 percent more in Mississippi than in DC, and the differences become even larger if metro area prices are considered instead of statewide averages. A person who makes $40,000 a year after tax in Kentucky would need to have after-tax earnings of $53,000 in Washington, DC just in order to have an equal standard of living, let alone feel richer.

As it happens, states with high incomes tend to have high price levels. This is hardly surprising, as both high incomes and high prices can correlate with high levels of economic activity. However, this relationship isn't strictly linear: for example, some states, like North Dakota, have high incomes without high prices. Adjusting for prices can substantially change our perceptions of which states are truly poor or rich.